

Right now we’re on a job in the East Falls section of Philadelphia, and it’s a good example of a situation we see more often than people expect. A buyer is under contract on a property, the home has visible mold, and the lender is requesting mold testing and inspection before the mortgage moves forward.
When a lender requests information about visible mold, an inspection may help document the property’s observed conditions. Advantage Mold provides mold inspection and testing in Philadelphia for buyers across the greater Philadelphia area, including buyers who are still under contract and do not yet own the property.
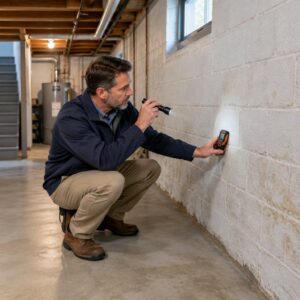
The tricky part in this East Falls case is that our buyer has no ownership interest yet, which raises real questions about access, timing, and what the lender will actually require before approving the loan.
Why Might a Lender Request Mold Testing?
Lenders request mold testing when visible mold or moisture damage raises a question about the property’s condition. A mortgage is secured by the home itself, so if there’s a concern that the structure has an unresolved issue, the lender wants documentation before committing funds.
Visible mold during an appraisal or walk-through is usually what triggers this. Once it’s noted, the file often gets flagged for further review before the loan can proceed to closing.
The lender may request a professional inspection or other documentation. Independent mold testing can provide additional information about the conditions observed, but the lender decides what it will accept and whether further steps are needed.
Watch: Mold Inspection and Mortgage Approval in Philadelphia
In this Short, Advantage Mold discusses a Philadelphia home purchase where the lender requested mold inspection and testing before the mortgage could move forward.
What Does Visible Mold Mean for a Pending Purchase?
Visible mold on a property under contract means the transaction now depends on getting clear answers before closing. It doesn’t mean the deal is dead, but it does mean the buyer, seller, and lender all need the same information at the same time.
Buyers may also find our guide to requesting mold clearance during a real estate transaction helpful.
Why Could the Mortgage Be Delayed?
The mortgage could be delayed because the lender wants to see the mold issue addressed, or at least clearly understood, before it finalizes the loan. Underwriters work off documentation, and an unresolved visible mold condition is a gap in that documentation.
That gap has to be filled with an inspection report before the file can move forward. Depending on the findings, the lender may ask for further remediation steps or additional verification before scheduling closing.
Who Decides What Must Be Resolved?
The lender decides what must be resolved, not the inspector and not the buyer. Advantage Mold’s role is to provide accurate, professional findings; what the lender does with those findings is entirely up to their own underwriting guidelines.
That’s an important distinction for buyers to understand going in. A thorough inspection report supports the process, but it doesn’t substitute for the lender’s own decision.
How Can a Buyer Arrange an Inspection Before Owning the Home?
A buyer can arrange an inspection before closing by getting explicit permission to access the property and coordinating the visit through the real estate agents involved in the transaction. See our guide to handling mold concerns during a home sale or purchase for more information.
Getting Permission to Access the Property
Permission typically comes through the seller, arranged with the listing agent’s cooperation. This keeps the visit on record and avoids any confusion about who authorized entry to a home the buyer doesn’t yet own.
In a case like this East Falls property, that permission needs to be secured before an inspection date can even be set. It’s a small step, but skipping it can stall the whole timeline.
Coordinating with the Seller and Real Estate Team
Coordinating the visit means looping in the buyer’s agent, the listing agent, and often the seller directly, so everyone knows when the inspector will be on-site and why. Being active in the real estate community day to day, this kind of coordination is familiar territory.
Clear scheduling keeps the transaction moving and prevents the kind of last-minute confusion that can push back a closing date that’s already under pressure.
What Should the Inspection Clarify?
The inspection should clarify exactly what the visible mold is, how extensive it is, and what’s causing it. That combination, condition plus cause, is what gives the lender something usable.
Documenting Visible Conditions and Test Results
Documentation starts with recording the visible mold itself: location, extent, and surface type. Test results then back up that visual record with lab-supported data on what’s present.
This pairing matters because a lender reviewing the file needs more than a photo of a stained ceiling. It needs a report that connects what’s visible to what the testing confirms.
Investigating Moisture and Other Underlying Causes
Mold growth is associated with moisture, so the inspection should consider the source of the moisture. If a plumbing leak is suspected, see our guide on what to do about mold from a leaking pipe.
Having an in-house HVAC technician and master plumber on staff means Advantage Mold can look at mechanical and structural factors directly during the same visit, rather than issuing a report that only names the mold and stops there.
What Happens After the Lender Receives the Findings?
The lender reviews the findings against its own underwriting criteria and decides what happens next. That could mean moving forward, requesting remediation, or asking for additional documentation.
Confirming the Lender’s Requirements
Confirming requirements means checking directly with the lender what specifically needs to happen for the loan to proceed. Every lender’s threshold is different, and the inspection report doesn’t set that bar, the lender does.
Buyers and agents should not assume that a clean report guarantees approval, or that a mold-positive report guarantees denial. The lender makes that call based on its own guidelines.
Addressing the Issue and Documenting the Outcome
Addressing the issue usually involves resolving the moisture source and any related mold growth identified in the inspection. Documenting that work, with before-and-after findings, gives the lender a clear record of what changed.
If remediation is recommended, learn more about mold remediation in Philadelphia
That documentation trail is what allows the file to move forward with confidence on all sides, buyer, seller, and lender alike.
How Advantage Mold Supports Philadelphia-Area Buyers
Advantage Mold supports Philadelphia-area buyers by providing building inspector-level mold testing and inspection for properties under contract, including situations where the buyer doesn’t yet own the home. Being consistently active in the local real estate community means this kind of transaction-timeline work is routine, not unfamiliar territory.
The in-house team, including an HVAC technician and master plumber, allows for a root-cause evaluation rather than a surface-level mold check. That’s the kind of detail that gives buyers, agents, and lenders a clearer picture of what’s actually going on inside a property like this one in East Falls.
Need to discuss a mold inspection for a home under contract? Contact Advantage Mold to discuss the property, access arrangements, and the documentation your lender has requested.